
Elevator & Escalator Market: Trends & Industry Outlook
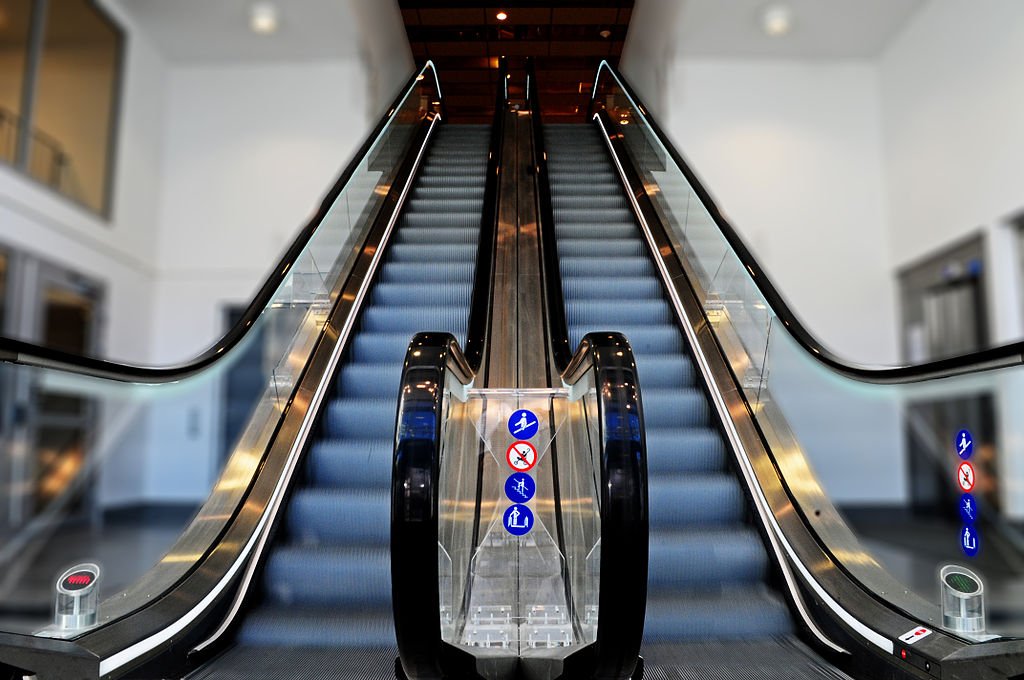
Global Elevator and Escalator Market Set to Reach USD 248.91 Billion by 2032 as Smart Urbanization, Vertical Infrastructure, and Modernization Overhauls Reshape City Mobility
𝐃𝐨𝐰𝐧𝐥𝐨𝐚𝐝 𝐏𝐃𝐅 𝐁𝐫𝐨𝐜𝐡𝐮𝐫𝐞 @ https://www.maximizemarketresearch.com/request-sample/17439/
Global urban centers are confronting an unprecedented spatial challenge. Rapid population influxes, accelerating demographic shifts toward dense metropolitan belts, and strict land-use constraints have made vertical expansion the foundational architecture of the modern built environment. In this evolving architectural reality, vertical and horizontal internal transport systems no longer serve as auxiliary mechanical conveniences; they act as the arterial transit networks of skyscrapers, mixed-use commercial developments, transit hubs, and modern residential communities. The global elevator and escalator market is undergoing a structural transformation, evolving from traditional mechanical pulley and truss assemblies into integrated, intelligent, energy-regenerative mobility nodes equipped with predictive algorithms, cloud telematics, and contactless interfaces.
According to research and market intelligence published by Maximize Market Research, the global Elevator and Escalator Market was valued at USD 160.18 Billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.5% through the forecast period from 2026 to 2032, reaching an estimated global market valuation of USD 248.91 Billion by 2032. This sustained capital expansion reflects two simultaneous industry forces: massive ongoing investments in mega-infrastructure, airport terminals, and transit interchanges across rapidly industrializing economies, coupled with an extensive, high-margin modernization cycle across aging installed equipment bases throughout mature Western metropolises.
As city planners, real estate developers, and municipal authorities rethink the environmental footprint, accessibility, and transit safety of tall buildings, vertical transit systems have emerged as a focal point for carbon mitigation and operational efficiency. The integration of permanent magnet synchronous motors, regenerative drives that feed kinetic deceleration energy back into municipal building grids, destination dispatch management, and artificial intelligence-driven predictive maintenance platforms is establishing an entirely new benchmark for internal building transit.
Executive Market Dynamics: Growth Drivers, Structural Headwinds, and Transformation Catalysts
The trajectory of the elevator and escalator market is dictated by an intersection of demographic, regulatory, engineering, and environmental factors that are redefining capital expenditure and lifecycle servicing models across the construction and property management sectors.
Rapid Global Urbanization and High-Density Vertical Living
The migration of populations from rural regions into secondary and primary urban clusters continues at an accelerated pace across Asia-Pacific, Latin America, and the Middle East. With horizontal urban sprawl constrained by agricultural preservation policies, suburban zoning limits, and land costs, municipal master plans prioritize high-density vertical master plans. Mega-skyscrapers and multi-tower residential developments require high-speed elevators featuring advanced destination control systems that group passengers logically by floor, maximizing cabin transit capacity, eliminating transit bottlenecks, and shortening waiting times during peak traffic periods.
Major Public Infrastructure Investments and Transit Hub Expansions
Governments worldwide are allocating billions to modernize international airports, expand underground metro transit stations, and construct intermodal high-speed rail terminals. Escalators and moving walkways represent mission-critical public assets in these spaces, operating continuously under intense passenger loads. Public transport authorities require heavy-duty, weather-resistant, continuous-duty escalator trusses and moving walkways designed with redundant mechanical braking systems, smart slip-detection sensors, and energy-conserving intermittent slow-run modes to handle high passenger flows safely.
Expanding Modernization and Aftermarket Replacement Cycles in Developed Nations
In regions like North America and Western Europe, thousands of operating elevators and escalators have exceeded their intended 20- to 25-year operational lifecycles. Operating older hydraulic and geared systems incurs high maintenance costs, consumes excess electrical power, and exposes building owners to regulatory penalties under upgraded municipal safety standards. Rather than complete structural tear-downs, property owners are executing deep modernization projects: replacing aging controllers with microprocessors, installing machine-room-less (MRL) modular assemblies, updating cab interiors, and integrating destination dispatch, extending asset lifespans while lowering electrical utility usage.
Tightening Building Energy Efficiency Codes and Green Building Certifications
Building emissions represent a substantial share of global carbon output, prompting governments to enforce rigorous building performance benchmarks, such as LEED, BREEAM, and WELL standards. Traditional elevators and escalators were notorious energy drains, dissipating considerable heat through mechanical friction and resistive braking boxes. Modern gearless traction systems, paired with bidirectional regenerative drives, capture the energy generated when a heavily loaded cab moves down or a lightly loaded cab ascends, converting kinetic momentum into clean AC electrical power that can be used directly by the building's lighting and ventilation systems.
Maintenance Bottlenecks, Safety Liabilities, and Skilled Technician Scarcity
Despite high market demand, the vertical transportation industry faces structural challenges. Complex mechanical maintenance, stringent municipal safety compliance, and the constant threat of passenger entrapment or catastrophic brake failure impose heavy liability burdens on building owners and service providers. Compounding these operating pressures is an acute shortage of certified elevator technicians and electro-mechanical mechanics in major mature markets. This labor deficit has driven emergency service costs up and created long repair backlogs, pushing building portfolios toward original equipment manufacturers (OEMs) that provide automated remote monitoring, continuous IoT telematics, and automated diagnostic tools.
Comprehensive Market Segmentation Analysis
The global elevator and escalator market is segmented by product type, service model, technology framework, and end-use application, each showing distinct growth characteristics and capital deployment patterns.
By Product Type
-
Elevators: The largest commercial product category, commanding dominant market share across all geographical sectors. Elevators are categorized into passenger elevators, freight elevators, vehicle elevators, and specialized hospital stretcher systems. The passenger segment remains the primary volume driver, while demand for heavy-duty freight elevators is expanding rapidly due to the proliferation of multi-story automated urban logistics warehouses and e-commerce distribution facilities.
-
Escalators: Representing essential internal transit systems across retail shopping centers, department stores, public entertainment stadiums, convention complexes, and mass transit terminals. Escalators are segmented into commercial, heavy-duty public transit, and outdoor weather-protected configurations, with heavy-duty public transit units showing robust long-term demand due to extensive airport and railway modernizations.
-
Moving Walkways (Travelators): Comprising both horizontal and inclined configurations widely integrated into expansive international airport concourses, hypermarkets, and multi-terminal rail hubs to speed up pedestrian flow and support luggage-laden passenger movements.
By Service Model
-
New Installations: Driven heavily by new real estate construction, public infrastructure schemes, and real estate master plans throughout developing urban corridors across India, Southeast Asia, China, and the Middle East.
-
Maintenance and Repair: The primary recurring cash-flow generator for equipment manufacturers and independent service providers. Equipment installations establish long-term service contracts that span decades, generating stable, high-margin, recession-resilient revenues through routine lubricating, parts replacement, emergency repairs, and mandatory annual safety certifications.
-
Modernization: The fastest-growing service segment in value terms across mature markets. Includes controller upgrades, cabin refurbishments, motor and drive replacements, safety gear modernizations, and door-operator replacements that improve safety, aesthetics, and energy efficiency without requiring civil shaft restructuring.
By Technology and Drive Architecture
-
Traction Elevators: Dominating medium-to-high-rise vertical construction. The segment has pivoted heavily from geared motors to gearless machine-room-less (MRL) configurations. MRL traction technology eliminates the requirement for dedicated rooftop penthouses, freeing up valuable top-floor penthouse square footage for building developers while delivering high operational energy efficiency and smooth acceleration.
-
Hydraulic Elevators: Retaining steady application in low-rise residential structures, low-traffic corporate campuses, and short-rise industrial freight applications under four to five stories due to their lower initial capital acquisition costs and simple mechanical layout, although their higher energy consumption limits their adoption in eco-certified projects.
-
Machine-Room-Less (MRL) Systems: The dominant global engineering configuration for low-to-mid-rise buildings, integrating compact gearless traction machines directly inside the hoistway shaft walls, eliminating structural concrete machine rooms and lowering initial structural engineering costs.
By End-Use Application
-
Residential: Representing the largest volume sector globally, fueled by affordable housing developments, high-rise luxury condominium towers, and suburban multi-family gated communities.
-
Commercial: The highest-value sector, encompassing Grade-A office towers, luxury hotels, corporate headquarters, and retail complexes. Commercial buyers require premium aesthetic finishes, high transit speeds, destination control dispatch systems, and integrated security turnstile integrations.
-
Infrastructure and Public Transport: Airport terminals, subway stations, rail terminals, and pedestrian overpasses demanding heavy-duty, vandal-resistant, and continuous-run escalators and moving walkways.
-
Institutional and Industrial: Specialized medical clinics, surgical centers, pharmaceutical plants, manufacturing campuses, and chemical refineries requiring oversized cabs, explosion-proof components, and advanced micro-leveling precision to safely transport sensitive gurneys, cleanroom components, and industrial pallets.
Regional Market Footprints and Geographic Insights
Asia-Pacific: The World's High-Volume Manufacturing and Consumption Engine
The Asia-Pacific region dominates the global elevator and escalator market in volume and revenue, accounting for more than half of the worldwide installed base and annual new equipment demand. China remains the world's largest individual market for new equipment sales and manufacturing, underpinned by state-supported urban renewal initiatives, high-speed rail network extensions, and municipal transit expansion. Concurrently, India has emerged as the fastest-growing market globally, propelled by nationwide initiatives such as the Smart Cities Mission, massive metro rail systems deployed across dozens of tier-1 and tier-2 cities, and a booming residential real estate market catering to a rising middle class. Furthermore, Southeast Asian economies—including Indonesia, Vietnam, and Malaysia—are experiencing construction surges, driving sustained demand for passenger elevators and commercial escalators.
North America: High-Value Modernization, Smart Buildings, and Stringent Safety Standards
North America represents a mature, high-value market characterized by intense capital allocation toward commercial modernization, smart building retrofits, and premium residential towers. The United States and Canada host vast installed equipment bases, much of which was installed decades ago. Consequently, the regional market is dominated by comprehensive aftermarket service contracts, digital IoT integrations, and mechanical modernization projects designed to comply with evolving American Society of Mechanical Engineers (ASME A17.1) safety codes. North American property developers are also leading adopters of touchless smartphone access controls, antimicrobial cabin surfaces, and predictive cloud-based maintenance architectures.
Europe: Technological Leadership, Sustainability, and Energy Retrofits
Europe represents a cornerstone of engineering excellence, housing the global headquarters of top elevator conglomerates, including Schindler Group and KONE Corporation. The European market is defined by strict regulatory frameworks governing equipment accessibility (EN 81-70), energy performance, and workplace safety. With thousands of historic buildings across Germany, France, the United Kingdom, Italy, and Spain requiring vertical accessibility retrofits, European engineering favors compact MRL systems and specialized architectural solutions that integrate within narrow, historic stairwells without disrupting external masonry facades. Furthermore, the European Union's aggressive net-zero building directives are compelling property managers to systematically replace old hydraulic units with regenerative gearless traction systems.
Latin America and Middle East & Africa: High-End Architectural Wonders and Regional Hubs
The Middle East represents a premier global showcase for extreme vertical transportation, with the United Arab Emirates, Saudi Arabia, and Qatar commissioning record-breaking architectural marvels, ultra-luxury mixed-use towers, and massive transport hubs. Large-scale mega-projects, such as those developing across the Gulf Cooperation Council (GCC) corridor, mandate customized, ultra-high-speed double-deck elevators capable of traveling at speeds exceeding 10 to 12 meters per second. In Latin America, expansion is anchored by urban residential consolidation in Brazil, Mexico, and Chile, alongside expanding industrial transit hubs and shopping mall complexes across regional metropolitan capitals.
The Future Business Role: Transforming into Intelligent Mobility-as-a-Service (MaaS)
The elevator and escalator manufacturing and servicing sector is moving away from the traditional model of one-off hardware sales followed by periodic break-fix repair visits. To secure long-term enterprise value and build durable gross margins through 2032, industry leadership must pivot toward integrated, software-enabled business models built on four pillars:
1. Monetizing the Digital IoT and Predictive Maintenance Layer
The primary profit engine of the future elevator industry resides in remote telematics and predictive intelligence. By outfitting motors, guide rails, door operators, and brake shoes with industrial vibration, thermal, and acoustic sensors, manufacturers stream operational telemetry directly into cloud analytics engines. Machine-learning models identify mechanical wear patterns, misalignments, or thermal anomalies days before a component fails. This shifts operational execution from reactive breakdown handling to planned, predictive interventions, cutting equipment downtime, optimizing technician scheduling, and allowing OEMs to command premium recurring service subscription fees.
2. Destination Dispatch Optimization and Contactless User Experiences
Modern high-rise commercial structures require intelligent traffic routing. Advanced destination control algorithms evaluate passenger traffic dynamically, routing passengers with shared destinations into dedicated cars to reduce intermediate stops, accelerate round-trip cycles, and lower building energy consumption during morning rush hours. Furthermore, post-pandemic workplace standards have normalized contactless building interactions. Integrating facial recognition scanners, smartphone Bluetooth beacons, and QR-code access credentials directly with elevator controllers provides seamless, secure movement from perimeter security turnstiles directly to the tenant's office floor without pressing a single physical button.
3. Integrated Microgrid Nodes and Carbon Neutrality Contributions
In next-generation smart cities, an elevator system must function as a dynamic microgrid node rather than a passive electrical load. Elevators equipped with regenerative drives, local supercapacitors, and lithium backup batteries can store regenerative braking power captured during passenger travel, deploying that stored energy during peak grid tariff hours to shave building utility spikes or providing emergency backup power to gently return cars to the nearest landing floor during municipal power outages without requiring heavy diesel generator infrastructure.
4. Advanced Digital Twins and Building Information Modeling (BIM)
Equipment manufacturers must integrate their engineering workflows directly into modern architectural software. By offering comprehensive Building Information Modeling (BIM) libraries and digital twin simulations, manufacturers allow architects and structural engineers to model dynamic passenger flows, structural shaft loads, wind-sway harmonic interactions, and electrical power demands during the conceptual design phase. This end-to-end digital integration eliminates expensive structural rework during physical construction and locks in proprietary equipment specifications early in the procurement cycle.
Strategic Decision-Making Framework for Real Estate Executives, Facility Directors, and Investors
Corporate strategists, institutional property developers, and asset managers making capital allocations in the vertical transportation domain should align their decisions with clear operational frameworks:
-
Prioritize Total Cost of Ownership (TCO) Over Initial Equipment Purchase Price: Selecting lower-cost, lower-efficiency elevator hardware frequently leads to higher lifetime operating expenses due to excessive utility consumption, frequent component wear, and costly proprietary replacement parts. Decision-makers must evaluate equipment based on 20-year operational lifecycle models, factoring in energy efficiency ratings, component modularity, and the availability of open-source diagnostic tooling.
-
Establish Multi-Protocol, Non-Proprietary Maintenance Compatibility: Property managers must ensure that newly commissioned elevator control systems utilize open, non-proprietary diagnostic architectures. Over-reliance on strictly proprietary controller software locks building owners into monopolistic service contracts with a single OEM, removing competitive leverage during contract renewals and driving up long-term operational maintenance costs.
-
Accelerate Modernization of Aging Equipment Assets: In high-cost urban real estate markets, maintaining dated, sluggish, and frequently stalled elevator banks directly depresses commercial tenant retention and property rental values. Proactively allocating capital to upgrade drive packages, door operators, and cabin interiors yields immediate returns through improved tenant satisfaction, reduced utility bills, and lower commercial property liability insurance premiums.
-
Integrate Smart Security and Building Automation Protocols: Asset managers must select elevator management systems that communicate smoothly with broader Building Management Systems (BMS) through open industrial protocols such as BACnet and Modbus. Unifying elevator traffic data with HVAC ventilation, smart lighting, and enterprise access-control security systems allows building managers to optimize occupancy management and lower facility carbon footprints.
For full access to the comprehensive strategic report, visit: https://www.maximizemarketresearch.com/market-report/global-elevator-and-escalator-market/17439/
Competitive Landscape and Key Industry Participants
The global elevator and escalator market is dominated by a core tier of international engineering conglomerates alongside high-growth regional innovators:
-
Otis Worldwide Corporation (United States) – The world's largest dedicated manufacturer and service provider of vertical transportation systems, celebrated for its iconic Gen2 and Gen3 machine-room-less platforms and Otis ONE IoT predictive maintenance service architecture.
-
Schindler Group (Switzerland) – Global pioneer in smart urban mobility, world-renowned for its innovative PORT technology destination dispatch systems, cleanroom escalators, and building transit modernization programs.
-
KONE Corporation (Finland) – Recognized technological pioneer in vertical transit, credited with commercializing the first machine-room-less elevator concept (KONE MonoSpace) and leading modern digital building integrations via KONE 24/7 Connected Services.
-
TK Elevator (TKE) (Germany) – Major multinational innovator, globally renowned for its multi-car MULTI rope-free horizontal-vertical system, TWIN dual-cabin elevators, and MAX cloud-based predictive maintenance platform.
-
Mitsubishi Electric Corporation (Japan) – Renowned world leader in ultra-high-speed vertical transit engineering, developing high-speed passenger elevators, spiraling architectural escalators, and advanced energy-saving drive packages.
-
Hitachi, Ltd. (Japan) – Leading global provider of high-speed passenger elevators, advanced traffic dispatch algorithms, and integrated building automation systems across Asia and global export hubs.
-
Fujitec Co., Ltd. (Japan) – Specialized engineering innovator delivering custom elevator, escalator, and moving walkway solutions tailored for luxury commercial developments and high-capacity transit terminals.
-
Hyundai Elevator Co., Ltd. (South Korea) – Major regional manufacturer providing advanced high-speed elevators, automated logistics systems, and smart predictive maintenance ecosystems across East Asia and international markets.
-
Toshiba Elevator and Building Systems Corporation (Japan) – Established pioneer in ultra-high-speed elevator drives, energy-efficient permanent magnet systems, and advanced earthquake-sensing safety controls.
-
Johnson Lifts Pvt. Ltd. (India) – Prominent regional manufacturer dominating the residential, commercial, and mass transit infrastructure sectors across the Indian subcontinent.
These market participants are actively competing by expanding regional production hubs, acquiring independent maintenance service providers to expand their recurring contract portfolios, and investing heavily in software engineering to deploy advanced artificial intelligence throughout their predictive service platforms.
Concluding Strategic Outlook
The Global Elevator and Escalator Market has moved far beyond its mechanical roots. Today, vertical transportation systems represent the core mobility nervous systems that make high-density, low-carbon urban living possible. As megacities expand upward, consumer preferences demand touchless, intuitive building transit, and municipal regulations penalize inefficient building energy consumption, intelligent elevators and escalators will define the future of architectural engineering.
Driven by a steady 6.5% CAGR and advancing toward a global valuation of USD 248.91 Billion by 2032, the market offers substantial commercial opportunities for equipment manufacturers, digital service innovators, and building developers. Organizations that invest in energy-regenerative drives, remote predictive telemetry, and passenger-centric digital workflows today will capture dominant market shares, ensure regulatory compliance, and help build the smart, sustainable cities of tomorrow.
About Us
Maximize Market Research publishes sector forecasts, competitive analysis, and consulting insight for teams evaluating demand, competition, pricing, and growth strategy across high-value industries.
Contact Information
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: sales@maximizemarketresearch.com
