
Saudi Arabia Home Healthcare Market Share, Trends, Analysis & Forecast 2026-2034
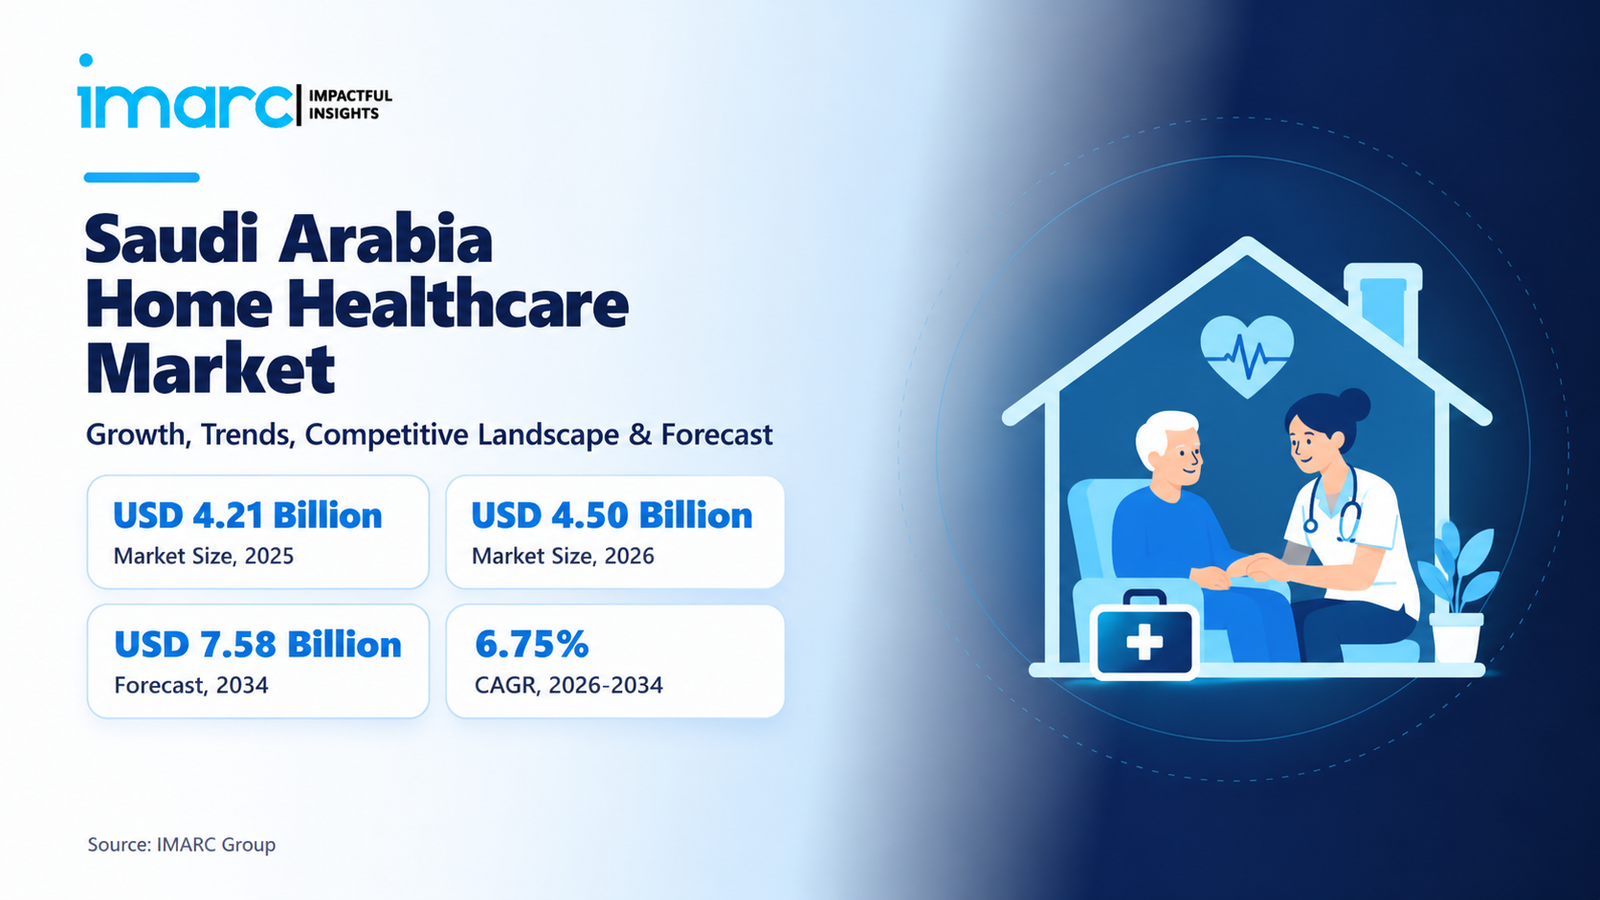
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Saudi Arabia home healthcare market. The Saudi Arabia home healthcare market size increased from USD 4.21 Billion in 2025 to USD 4.50 Billion in 2026 and is projected to reach USD 7.58 Billion by 2034, expanding at a CAGR of 6.75% during 2026-2034, driven by Vision 2030 healthcare privatization, a world-leading chronic disease burden, and mandatory health insurance expansion.
Home healthcare benefits from the structural nature of chronic disease management and hospital decongestion demand in Saudi Arabia, with every hospital discharge, long-term diabetes or hypertension patient, and aging household requiring sustained care outside the hospital walls. The market is forecast to add USD 3.08 Billion in incremental value between 2026 and 2034, with three structural forces shaping this trajectory: the government's objective to shift 30% of healthcare delivery from hospital to community settings, a chronic disease epidemic with 5.3 million diabetes cases in 2024, and a decisive expansion of CCHI-mandated insurance reimbursement for home care.
Saudi Arabia Home Healthcare Market at a Glance:
- Market Size (2025): USD 4.21 Billion
- Market Size (2026): USD 4.50 Billion
- Forecast Market Size (2034): USD 7.58 Billion
- CAGR (2026-2034): 6.75%
- Leading Product and Service (2025): Products, 57.3% share
- Leading Indication (2025): Cardiovascular Diseases and Hypertension, 18.6% share
- Fastest-Growing Segment: Services, approximately 8.2% CAGR
How AI is Reshaping the Future of the Saudi Arabia Home Healthcare Market
- AI-Powered Remote Patient Monitoring: AI-enabled remote patient monitoring platforms are collecting continuous home health data and generating automated care alerts for clinical teams, helping providers manage the Kingdom's large diabetes and cardiovascular patient populations while reducing avoidable hospital visits, with telehealth-integrated monitoring forecast to grow at approximately 25-30% CAGR from a 2025 base.
- Telehealth and AI-Assisted Clinical Decision Support: Seha Virtual Hospital is being integrated with licensed home healthcare providers, allowing home nurses and therapists to deliver physical care while connected by secure video to specialist physicians, and AI triage systems are prioritizing acute home patient consultations by severity.
- Smart, IoT-Connected Home Health Infrastructure: Connected glucose monitors, cardiac monitors, and smart home health systems are emerging as providers and developers, including NEOM's digital-first health design, target technology-integrated residential care for tech-savvy and high-income households.
Grab a sample PDF of this report: https://www.imarcgroup.com/saudi-arabia-home-healthcare-market/requestsample
Saudi Arabia Home Healthcare Market Trends and Drivers:
Saudi Arabia's chronic disease burden is the foundational driver behind the market's product-led structure, with 23.1% adult diabetes prevalence and over 5.1 million adults aged 30-79 living with hypertension generating continuous demand for home monitoring and therapeutic devices. Products lead the market at 57.3% share in 2025, supported by CCHI coverage of glucose monitors, blood pressure monitors, and nebulizers, while Cardiovascular Diseases and Hypertension hold the largest indication share at 18.6%, and Diabetes, at 15.9% share, is the fastest-growing indication as continuous glucose monitoring, insulin management, and foot care shift from clinics to homes.
Service expansion is compounding this product-led growth with the fastest segment-level momentum in the market. Services hold 42.7% share, equivalent to approximately USD 1.80 Billion, and are growing at approximately 8.2% CAGR through 2034 as CCHI benefit expansion converts home care from private-pay to insurance-reimbursed delivery. ADEED Medical Services Company announced its Joint Commission International (JCI) accreditation for Excellence in Home Healthcare in March 2025, while Saudi German Health Riyadh launched a hospital-to-home oncology care pathway with weekly telehealth check-ins by SGH oncologists, both reinforcing the shift toward accredited, hospital-integrated home care across the Kingdom.
Digital transformation and regional expansion are reshaping delivery economics on top of these demand drivers. The Northern and Central Region's dominant 31.4% share in 2025 reflects Riyadh's 8.2 million population and its status as the Kingdom's largest source of hospital discharge referrals, while the Western Region, at 27.6% share, is the fastest-growing region at approximately 7.2% CAGR as Jeddah's commercial economy and the Holy Cities' resident community sustain demand. A shortage of licensed home healthcare professionals remains the market's key constraint, with Saudization of the clinical workforce simultaneously creating a domestic talent pipeline that reduces dependence on expatriate recruitment.
Government Schemes and Vision 2030 Initiatives Driving Demand:
- Health Sector Transformation Program (HSTP): A core Vision 2030 program that identifies home healthcare as a critical pillar of hospital bed decongestion and cost sustainability, targeting a shift of 30% of healthcare delivery from hospital to community settings and generating sustained post-acute referral demand across the Kingdom.
- CCHI Mandatory Health Insurance Expansion: Progressive expansion of the Council of Cooperative Health Insurance framework, including expatriate workers under employer-mandated policies, has created the reimbursement infrastructure that makes home medical devices and home care services financially accessible to insured patients.
- National Health Insurance Scheme (NHIS): The planned expansion of the NHIS to Saudi nationals is expected to add further covered lives to the home healthcare reimbursement ecosystem by 2027, widening the addressable patient base for licensed providers.
- Seha Virtual Hospital and National Digital Health Integration: Integration of licensed home healthcare providers with Seha Virtual Hospital and the Unified National Health System is enabling digitally supervised home care and real-time access to discharge summaries, medication histories, and laboratory data.
- Saudization of the Healthcare Workforce: Vision 2030's Saudization target for healthcare, supported by HRDF training programs, is building a domestic clinical workforce pipeline that reduces home healthcare's dependence on volatile expatriate recruitment.
Saudi Arabia Home Healthcare Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Product and Service:
- Product
- Therapeutic Products
- Testing, Screening, and Monitoring Products
- Mobility Care Products
- Service
- Skilled Nursing
- Rehabilitation Therapy
- Hospice and Palliative Care
- Unskilled Care
- Respiratory Therapy
- Infusion Therapy
- Pregnancy Care
Products command a 57.3% majority share in 2025, spanning therapeutic devices such as insulin pumps, nebulizers, CPAP/BiPAP machines, and home oxygen concentrators, monitoring devices such as glucometers, CGM systems, and blood pressure monitors, and mobility aids such as wheelchairs, patient lifts, and hospital beds. Services hold 42.7% and are growing at approximately 8.2% CAGR as the fastest segment, with skilled nursing as the dominant sub-segment, followed by rehabilitation therapy, home infusion therapy, and hospice and palliative care.
Breakup By Indication:
- Cancer
- Respiratory Diseases
- Movement Disorders
- Cardiovascular Diseases and Hypertension
- Pregnancy
- Wound Care
- Diabetes
- Hearing Disorders
- Others
Cardiovascular Diseases and Hypertension dominate at 18.6% share in 2025, the largest home product category, sustained by over 5.1 million adults with hypertension and systematic demand for blood pressure monitoring, medication adherence programs, and cardiac rehabilitation visits. Diabetes holds 15.9% and is the fastest-growing indication, while Cancer holds 12.7% and grows at approximately 9-10% CAGR as home chemotherapy and palliative care programs expand nationally. Wound Care at 10.6%, Movement Disorders at 9.4%, Hearing Disorders at 7.8%, and Pregnancy at 6.5% complete the picture, with movement disorder physiotherapy and maternal home care growing above the market CAGR.
Breakup By Region:
- Northern and Central Region
- Western Region
- Eastern Region
- Southern Region
The Northern and Central Region commands 31.4% share in 2025, driven by Riyadh's 8.2 million population and the Kingdom's highest hospital discharge-to-home-care referral volume. The Western Region follows at 27.6% and is the fastest-growing at approximately 7.2% CAGR, sustained by Jeddah's commercial economy and the Makkah and Madinah resident community, while the Eastern Region holds 22.8% on the Dammam-Al Khobar-Dhahran cluster and Saudi Aramco's generous employee health insurance, and the Southern Region's 18.2% share offers a structural expansion opportunity as Vision 2030 rural health investments improve infrastructure and insurance coverage in Asir, Jizan, Najran, and Al Baha.
Competitive Landscape:
The Saudi Arabia home healthcare market is moderately concentrated among CBAHI-accredited licensed providers and highly fragmented among the broader universe of registered home healthcare agencies. The report provides detailed profiles of all major companies, including:
- Saudi German Health
- Saudi Medical Services Company - ADEED
- Dallah Health
- International Medical Center
Saudi German Health leads through its multi-city hospital network, which generates continuous post-discharge home care referrals, while ADEED is recognized for a modern, JCI-accredited model delivering integrated at-home medical services around the clock. Dallah Health and International Medical Center maintain established positions anchored in Riyadh and Jeddah hospital networks, and the top four providers collectively represent an estimated 35-40% of the organized home healthcare service market, with licensing requirements for CCHI-reimbursed care limiting informal market entry.
Market Concentration Analysis:
- Fragmentation: The market is moderately concentrated at the service provider tier and fragmented at the product distribution level; no single home medical device distributor controls more than 15% of total volume
- Segment Leadership: CBAHI-accredited providers account for approximately 70-75% of the insurance-reimbursable home service market, with Saudi German Health and ADEED recognized as market leaders
- Consolidation Trend: Integrated providers that combine product supply with clinical service delivery hold the most strategically valuable position in the value chain, and hospital-to-home partnerships and accreditation are increasingly central to competitive differentiation
What Does The Full Report Cover?
If you are tracking the Saudi Arabia home healthcare market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
- Complete market sizing in value terms with historical analysis for 2020-2025 and forecasts covering the full 2026-2034 projection period
- Detailed analysis of market drivers, restraints, opportunities, and challenges shaping home healthcare demand across the Kingdom
- Segment breakdowns across product and service categories, nine indication categories, and four regions, each with individual share and growth data
- Competitive profiles of Saudi German Health, Saudi Medical Services Company - ADEED, Dallah Health, and International Medical Center with strategic positioning analysis
- Value chain analysis, market concentration assessment, Porter's five forces analysis, and technology landscape coverage across telehealth, home infusion, and digital care management
- Latest trends covering telehealth-home care integration, AI-powered remote patient monitoring, maternal and neonatal home care, and NEOM smart home health infrastructure shaping market competition across the Kingdom
Recent News and Developments in Saudi Arabia Home Healthcare Market
- April 2026: The Third Annual International Home Healthcare Conference 2026 was registered as a hybrid event in Riyadh, reflecting growing industry focus on home-based care models, provider collaboration, and policy dialogue in the Kingdom.
- March 2025: ADEED Medical Services Company announced its achievement of Joint Commission International (JCI) accreditation for Excellence in Home Healthcare, adding to its CBAHI accreditation and reinforcing quality standards in the Kingdom's home care sector.
- January 2025: The Saudi Ministry of Health reported more than 58,000 active home care cases in a year and over 71,000 total beneficiaries since launch, delivered through 244 home healthcare departments with more than 2,700 specialized staff members.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current Saudi Arabia home healthcare market size and what is its projected value?
- Which product and service segment and indication hold the largest share in the Saudi Arabia home healthcare market?
- What are the key drivers of Saudi Arabia home healthcare market growth?
- Which region dominates the Saudi Arabia home healthcare market and which is growing fastest?
- How are Vision 2030's Health Sector Transformation Program and CCHI insurance expansion reshaping the Saudi Arabia home healthcare industry?
- Who are the top companies in the Saudi Arabia home healthcare market and what are their competitive strategies?
- What are the investment and market entry opportunities across home infusion therapy, remote patient monitoring, and workforce development in Saudi Arabia?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
